It is a separate policy
Fire is covered by your homeowners policy. Shaking is not. Earthquake insurance is its own policy that pays to repair or rebuild the structure, replace contents, and cover living costs while you are out.
Every homeowners and commercial property policy in California excludes earthquake damage. A separate earthquake policy pays to rebuild. We quote it for you, the California Earthquake Authority and private carriers alike, and show you what each one costs before you decide.
Quotes usually within 24 hours of a complete submission. No obligation.
Fire is covered by your homeowners policy. Shaking is not. Earthquake insurance is its own policy that pays to repair or rebuild the structure, replace contents, and cover living costs while you are out.
You do not write a check. The deductible comes off the top of the claim. On a $600,000 home with a 10% deductible and $250,000 of damage, you absorb $60,000 and the policy pays $190,000. Try the numbers.
Most people only ever see one quote: the California Earthquake Authority policy their home insurer offers. We quote that same CEA policy for you, and the private carriers that compete with it on deductible, limits and what they cover, on one submission, side by side.
Your homeowners policy and your commercial property policy both exclude earthquake. We place the coverage that fills that gap, and we shop it.
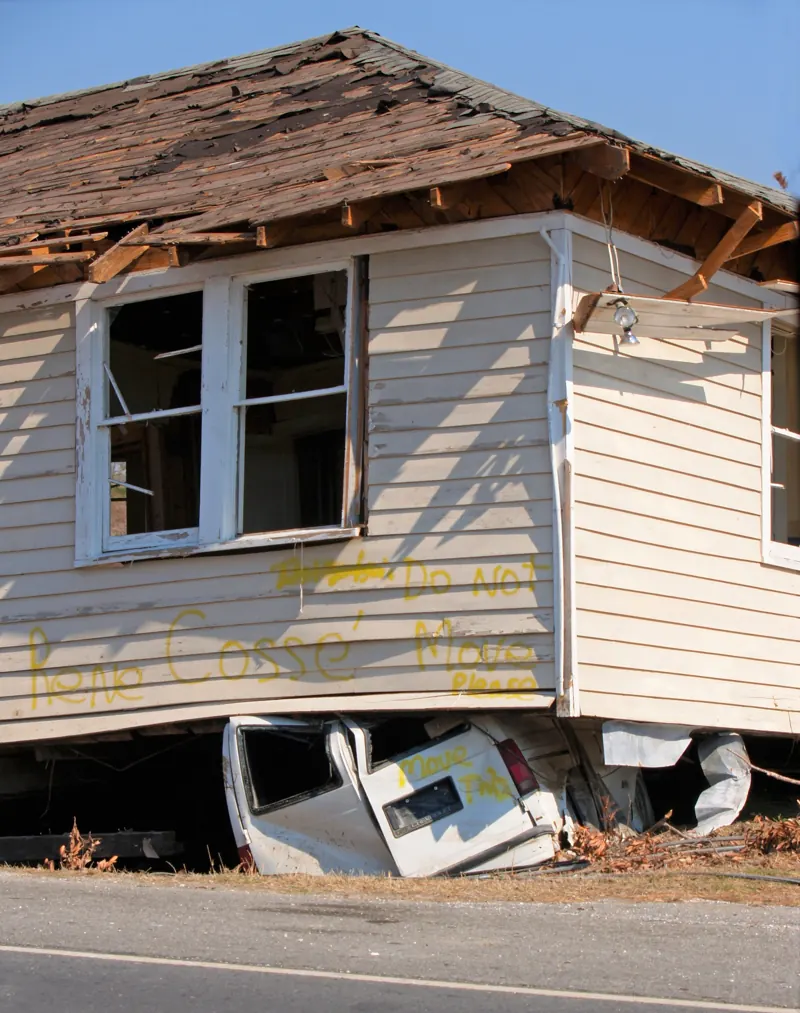
Single-family homes, condos, and rental property. More than seven carriers that specialize in residential earthquake, with deductibles and limits the CEA does not offer.
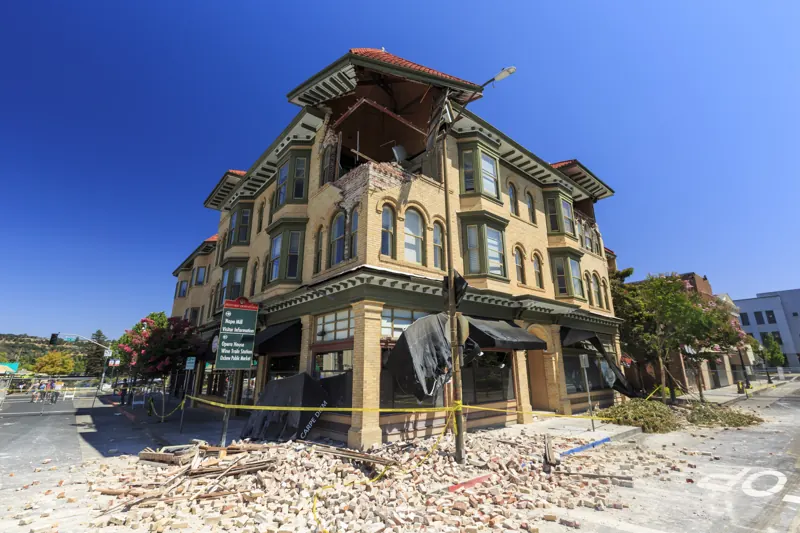
Retail, industrial, office, hospitality, multifamily and HOAs. Building, business personal property, and earthquake business interruption, placed with markets that understand PML and lender covenants.
Address, year built, construction, and the dwelling or building value. Five minutes on the form.
One submission goes to the CEA and to every private carrier that will write the risk.
Deductible, limits, contents, loss of use and premium, lined up so the trade-offs are plain.
Pick the option that fits. We handle the application, the lender, and the renewal.
Your home insurer can offer you one thing: the California Earthquake Authority policy. We can offer you that same CEA policy and the private carriers next to it, on one page, with the deductible, limits and premium lined up. You pick. That is the whole point of an independent broker.
Read the full comparisonMost people hear "15% deductible" and assume the policy never pays. Move the sliders. The deductible comes off the top of the loss, and the policy pays the rest up to your limit. The lower the percentage, the less you carry, which is why we quote private carriers alongside the CEA.
Example only. Actual claim payments follow the policy's terms, limits and sublimits.
Probability of a magnitude 6.7 or greater earthquake somewhere in California within 30 years.
Source to cite: USGS UCERF3 (2015). Verify before publishing.Insured losses from the 1994 Northridge earthquake, the costliest U.S. quake on record.
Source to cite: Insurance Information Institute or CDI. The live site says $25B; confirm which figure and whether it is insured or total.Share of California homeowners who carry earthquake insurance.
Source to cite: California Department of Insurance or CEA annual data. The live site renders this as "7 Percentage", which is broken.Six here. The full FAQ covers what is and is not covered, waiting periods, and how claims are paid.
For most California homeowners, earthquake insurance runs between $800 and $3,000+ per year. The biggest price drivers are your distance from active faults, soil type, the age and construction of your home, your dwelling coverage amount, and most of all the deductible you choose. Because we quote both the California Earthquake Authority (CEA) and multiple private carriers, we can usually find a meaningfully lower price for the same coverage than any single-company quote.
Often, yes, because the deductible is a percentage, not a wall. If your home is insured for $600,000 with a 10% deductible and an earthquake causes $250,000 in damage, you pay $60,000 and insurance covers the remaining $190,000. Without a policy, all $250,000 is yours. Earthquake insurance is catastrophic-loss protection: it exists so a bad earthquake doesn't take your home equity with it.
Frequently. CEA deductibles typically run 5–25% of dwelling coverage. Several private earthquake carriers we represent offer deductibles as low as 2.5–5%, higher dwelling limits, and broader personal property coverage. That comparison, CEA vs. private, side by side, is exactly what we do.
No. Standard commercial property policies exclude earthquake damage, just as homeowners policies do. Commercial earthquake coverage is a separate policy or endorsement, and for many California commercial buildings, lenders require it as a condition of the loan. We quote commercial earthquake for buildings, business personal property, and earthquake-related business interruption.
Insurers routinely impose a temporary moratorium on new earthquake policies immediately after a significant quake (often around 15–30 days, varying by carrier). Translation: you cannot buy this coverage while the ground is still moving. The time to secure a policy is before the event. Quotes are free and take minutes.
Yes, and it's usually inexpensive. Renters' earthquake coverage protects belongings and loss of use. For condo owners it's more urgent: your HOA's master policy often carries no earthquake coverage at all, and unit owners can be hit with enormous loss assessments to rebuild the structure. Condo earthquake policies with loss assessment coverage are one of the most under-purchased, highest-value policies we write.
Every commercial property policy written in California carries the same quiet exclusion. PML, soft-story retrofits, and lender requirements, explained.
GuideThe equity argument, the moratorium problem, and how to size a deductible you can actually absorb.
GuideWhat changes when the CEA is one option on the page instead of the only one.
Carriers stop writing new policies for weeks after a significant earthquake. A quote takes minutes and costs nothing.